

Are you noticing unusual cracks in your home? Worried they might be signs of subsidence? You're not alone. Many homeowners across the UK face this alarming issue which can lead to significant structural damage if left unaddressed. In this comprehensive guide, we'll cover everything you need to know about subsidence cracks. From identifying early signs to understanding the causes and exploring solutions, we've got you covered. Whether you're a concerned homeowner or simply curious, this guide is tailored to help you recognise, treat, and prevent subsidence in your property.
The short answer: subsidence cracks are usually diagonal, wider at the top than the bottom, more than 3mm wide (roughly the thickness of a £1 coin) and visible both inside and outside, often around doors and windows. Fine cracks that stay the same width are far more common and usually cosmetic.
In this blog
- What is subsidence and how do you identify it?
- When should you worry about a crack?
- How do you treat and prevent subsidence?
- What causes subsidence?
- How much does subsidence cost to fix?
- Selling or buying a home with subsidence
- Can you claim on insurance?
- Subsidence cracks FAQs
What is Subsidence and How to Identify It
Subsidence occurs when the ground beneath a building shifts or sinks, pulling the foundations down with it and leading to structural issues. Recognising subsidence early can save you from costly repairs. Here are key indicators:
- Cracks in walls: Look for wide, diagonal cracks, especially around doors and windows. These are often the first signs of subsidence.
- Uneven floors: Floors that start to slope or become uneven can indicate ground movement.
- Sticking doors and windows: If doors and windows become misaligned or difficult to open and close, subsidence could be the culprit.
Understanding what subsidence looks like is crucial for early detection and prevention of further damage.
Types of Cracks
- Hairline Cracks: These are very fine cracks, usually less than 1mm in width. They can be a normal part of a building settling but should be monitored for changes.
- Minor Cracks: Cracks up to 5mm wide. These might not be serious but should be inspected if they appear suddenly or grow over time. The Royal Institution of Chartered Surveyors (RICS) says there is rarely real cause for concern unless a crack appears suddenly and is more than 3mm wide.
- Moderate Cracks: Cracks of 5mm to 15mm. These need opening up and repairing, and can affect weather-tightness, so get them assessed.
- Severe Cracks: Cracks over 15mm wide. These are a strong indication of significant movement and require immediate professional attention.
Surveyors and engineers commonly grade cracking using the Building Research Establishment (BRE) damage categories:
| BRE category | Approximate crack width | What it typically means |
|---|---|---|
| 0 | Less than 0.1mm | Hairline cracks. No repair needed. |
| 1 | Up to 1mm | Fine cracks, generally in internal finishes. |
| 2 | Up to 5mm | Cracks easily filled. Still cosmetic. |
| 3 | 5mm to 15mm | Cracks need opening up. Weather-tightness and pipes may be affected. |
| 4 | 15mm to 25mm | Extensive damage. Door and window frames distort, walls lean or bulge. |
| 5 | More than 25mm | Structural damage. Walls may need shoring. |
Source: BRE Digest 251, summarised by Designing Buildings. Whether a crack is getting wider matters as much as its width.
Internal and External Signs
- Internal Signs: Aside from cracks, look for doors and windows that don’t fit their frames properly, ripples in wallpaper that aren’t caused by damp, gaps between walls and ceilings or skirting boards, and sloping floors.
- External Signs: Check for cracks in the brickwork, especially those that are wider at the top than at the bottom, gaps between bricks, cracks where an extension joins the main house, and movement in the foundation.
Subsidence Cracks on Internal Walls
Indoors, subsidence cracks usually show in the plaster above and around door frames and windows. A diagonal crack running from the corner of a door frame that lines up with a crack in the same spot outside is a much stronger warning sign than one in the plaster alone. Fine vertical or horizontal cracks of even width, especially in new or recently plastered walls, are usually just materials drying out or seasonal movement. Rippled wallpaper is more often damp than subsidence, so see our guide to combatting condensation and damp if the wall also feels cold or shows mould.
Detailed Indicators
- Pattern of Cracks: Subsidence cracks often follow a stair-step pattern in brickwork. Stepped and diagonal cracks of any width are worth having checked.
- Width and Taper: Measure the width of the cracks. Subsidence cracks are usually wider than superficial cracks and tapered, wide at one end and narrow at the other.
- Seasonal Changes: Observe if cracks widen during dry periods and close up during wetter months. This can indicate soil shrinkage and expansion causing subsidence.
When Should You Worry About a Crack?
Most cracks are not subsidence. Guidance from the Association of British Insurers (ABI), RICS and NHBC says get a crack checked if it:
- is wider than 3mm, roughly the thickness of a £1 coin
- is diagonal, stepped or wider at one end
- appeared suddenly or is getting wider or longer
- shows on both the inside and outside of the same wall
- runs below the damp proof course, or appeared as doors or windows started to stick
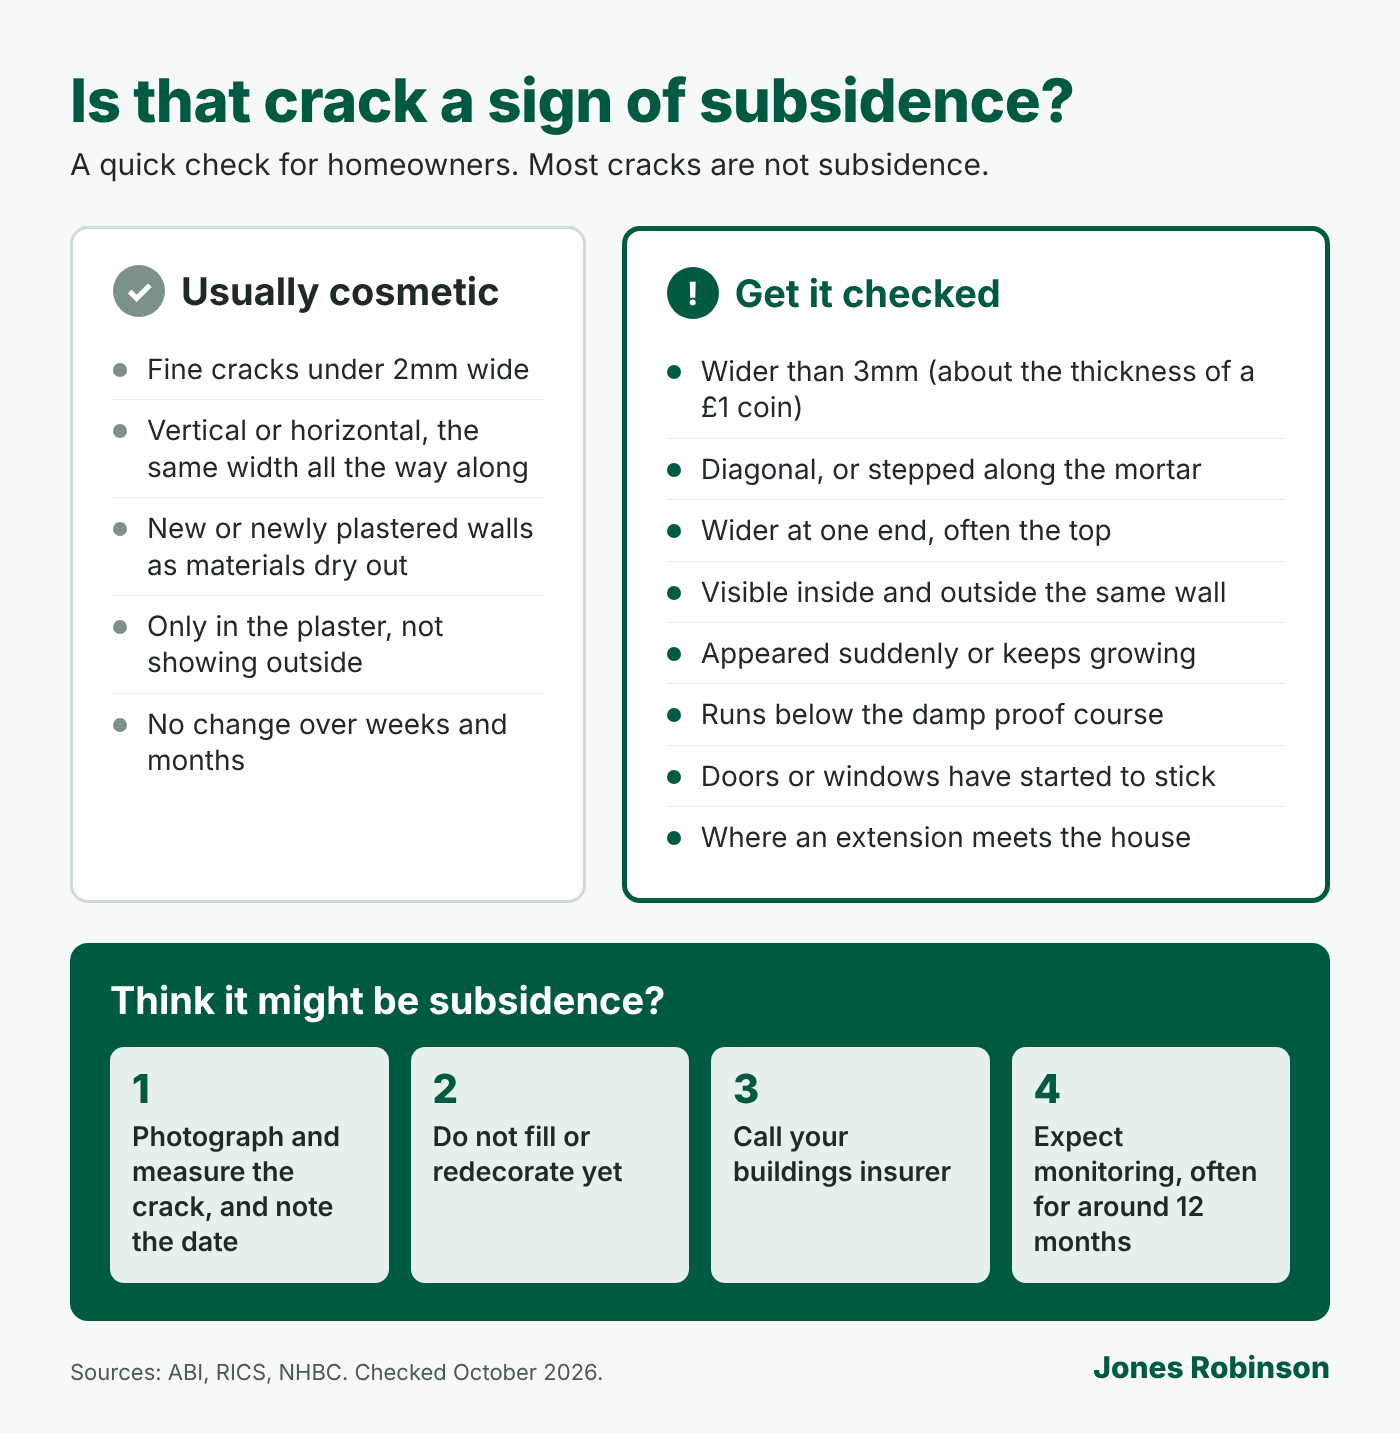
To track a crack, pencil-mark both ends with the date and photograph it next to a ruler every few weeks. One that has not changed in months is far less of a worry than one that is growing.
Subsidence, Settlement or Heave?
Settlement is the ground compacting under a newer building and soon stabilises, which is why fine cracks in new homes are common. Heave is the ground rising as clay swells, for example after a large tree is removed, and tends to cause vertical cracks. Insurance generally covers subsidence and heave but not normal settlement.
How to Treat and Prevent Subsidence
Immediate Actions
If you suspect subsidence, contact your buildings insurer as soon as possible. Insurers usually appoint their own engineer or loss adjuster, so check before paying for a report. If you are not insured, or want independent advice, contact a structural engineer or RICS surveyor for a professional assessment. Early intervention can mitigate further damage. Meanwhile, photograph and measure the cracks and do not fill them until they have been inspected.
Long-term Solutions
- Removing the cause: Most cases are resolved by repairing leaking drains or managing a tree that is drying out clay soil, then repairing the cracks once movement stops.
- Underpinning: This involves strengthening the foundation to stabilise the structure. It is used for severe or ongoing subsidence, but RICS says fewer than 5% of affected properties need it. Work near a neighbour's foundations may need a party wall agreement.
- Improving Drainage: Poor drainage can exacerbate subsidence. Ensuring gutters and downpipes are clear can help prevent water accumulation around the foundation.
Preventative measures are often more cost-effective than dealing with advanced subsidence.
DIY Prevention Tips
- Tree Management: Plant trees and shrubs away from the house to prevent roots from affecting the soil under your foundation. Thirsty species such as oak, willow and poplar can dry clay out to a distance roughly equal to their height. Get an arboriculturist's advice before pruning or felling, as removing a mature tree on clay can cause heave. Trees with a Tree Preservation Order or in a conservation area need council consent or six weeks' notice before any work.
- Drains and Pipes: Get leaking drains, split downpipes and damp patches near the house fixed promptly, as escaping water can soften or wash away soil under foundations.
- Regular Inspections: Conduct regular inspections of your property for early signs of subsidence, particularly after a long, dry summer. Early detection is key to preventing serious damage.
What Causes Subsidence?
Understanding the causes of subsidence can help in both prevention and treatment. Here are the primary factors:
Cracking is common in properties that have stood empty, so if you are considering one, read our tips for buying a derelict property alongside this.
Soils
Certain soil types, like clay, are more prone to subsidence. Clay soils expand when wet and contract when dry, causing ground movement.
- Clay Soils: Highly susceptible to changes in moisture content. They expand when wet and contract when dry, leading to ground movement. Hot, dry summers make this worse.
- Sandy and Gravelly Soils: These do not shrink like clay, but leaking drains and water mains can soften them or wash them away.
- Peaty Soils: Can compress and decompose over time, leading to subsidence.
Locally, ground conditions vary over short distances. Much of the North Wessex Downs is chalk, the Kennet valley has river gravels, and a narrow band of Gault Clay runs along the northern foot of the downs, historically dug for bricks around Devizes. When you buy, the environmental search usually flags known ground stability risks, as our guide to the three main searches when buying a house explains.
Drainage Problems
Leaks from pipes or inadequate drainage can soften the soil, making it unstable.
- Broken or leaking pipes can wash away or erode soil beneath the foundations, leading to voids and subsidence.
- Inadequate drainage systems can cause water to accumulate around the foundation, leading to soil saturation and instability.
Tree Roots
Large trees close to a property can absorb significant amounts of water from the soil, leading to shrinkage and subsidence. RICS cites a Which? estimate that around 70% of subsidence cases are caused by tree roots drawing moisture from shrinkable soil.
- Tree roots can extract large volumes of water from the soil, causing it to shrink and destabilise foundations.
- Roots can also get into older drains with poor seals, which then leak and soften the ground.
Costs
The cost of treating subsidence can vary widely based on the severity and chosen method of repair. Underpinning can be particularly expensive, often running into tens of thousands of pounds. Early detection and minor repairs can save money in the long run.
Breakdown of Costs
| Item | Typical cost |
|---|---|
| Structural engineer inspection | £175 to £300 |
| Structural engineer’s report | £500 to £2,000 |
| Underpinning a house | £10,000 to £75,000, more for larger homes |
| Average insured subsidence claim | £20,000 (April to June 2026, a record) |
| Typical subsidence excess | Around £1,000 |
Sources: Federation of Master Builders (engineer fees, July 2026), RICS (underpinning), ABI (claims and excess). Always get quotes.
Fixing a drain or managing a tree is usually far cheaper than foundation work, and if an insurance claim is accepted you normally pay only the excess.
Aesthetic Impacts
Subsidence can severely affect the appearance of your home, with visible cracks and structural distortions. Repairing these damages can restore the aesthetic value of your property, making it look well-maintained and safe.
Cosmetic Repairs
- Once structural issues are resolved and movement has stopped, replastering and repainting walls can restore their appearance.
- Repointing or replacing damaged bricks ensures the exterior looks as good as new.
Consequences if Not Dealt With
Ignoring subsidence can lead to significant structural damage, and the longer movement continues, the bigger the repair bill. It can also lower property value and make selling difficult. Caught early, subsidence can usually be put right.
Potential Risks
- Continued subsidence can lead to major structural issues, from distorted frames to walls that lean, bulge or, in the most severe cases, need shoring up.
- Homes with unresolved subsidence issues can see a significant drop in market value.
- In severe cases, structural instability poses a significant safety risk to the occupants.
- Insurers expect you to report damage when you first become aware of it, so delay can put your cover at risk.
Financial Implications
Dealing with subsidence can be costly, but the financial implications of ignoring it are even greater. Properties with untreated subsidence issues often see a reduction in market value and increased insurance premiums.
Long-term Costs
- Properties with a history of subsidence may face higher insurance premiums or difficulty obtaining coverage. Your existing insurer will normally continue cover, but if you need a new policy a specialist broker can help.
- Subsidence can make a property less attractive to buyers, significantly lowering its resale value.
Selling a Home With Subsidence History
Past subsidence does not stop a sale, but you must be open about it. The Law Society's Property Information Form (TA6) asks sellers about insurance claims made during their ownership and works needed to fix known defects, and incorrect answers can let a buyer claim compensation or refuse to complete. Have the engineer's report, repair details, any guarantees and confirmation that the claim is closed ready. Our partner solicitors, through our conveyancing services, can advise on disclosure.
Buying a Home That Has Had Subsidence
Ask when, why and how it was fixed, and speak to your lender and an insurer or broker before committing. Our mortgage advice team can help you find a lender comfortable with the property's history. For a home with signs of past movement, a Level 3 survey is the safer choice. See our guide to Level 2 vs Level 3 surveys.
Can You Claim on Insurance?
Most buildings insurance policies cover subsidence, but it’s essential to check the specifics of your policy. Claiming on insurance can help mitigate the costs associated with subsidence repairs. Ensure you document all signs of damage and consult with your insurer promptly.
Claiming Process
- Keep detailed records of all visible damage and any repairs undertaken.
- Contact your insurance company to understand the process and coverage. Most insurers send their own engineer or loss adjuster, so you may not need to commission your own structural engineer’s report.
- Where movement is ongoing, expect monitoring for around 12 months. Full investigation and repair can take up to two years.
- Expect to pay an excess, usually around £1,000 and sometimes more if the home has had subsidence before. Garden walls, fences, patios and driveways are not usually covered unless damaged at the same time as the house.
If you report subsidence within eight weeks of switching insurer, your previous insurer will handle the claim under an industry agreement, so tell your new insurer straight away if you spot cracks soon after changing policy.
Subsidence is a serious issue that requires immediate attention. By understanding the signs, causes, and solutions, you can protect your home from significant damage. Regular inspections and early intervention are key to managing this problem effectively.
Subsidence Cracks FAQs
What do minor subsidence cracks look like?
Usually thin diagonal cracks running from the corners of doors and windows, slightly wider at the top. Even a narrow crack that is new, tapered and visible inside and out is worth reporting.
Is a 1mm or 2mm crack a sign of subsidence?
Usually not. NHBC treats cracks of 2mm or less as generally cosmetic, especially if they are vertical or horizontal and stay the same width. Fill them, but watch for any growth.
Should I fill a crack before my insurer inspects it?
No. Wait until the cause has been confirmed. Filling it hides evidence, and the crack may reopen if the ground is still moving.
Talk to Your Local Jones Robinson Branch
If you suspect your home is showing signs of subsidence, don't wait. Speak to your buildings insurer or a professional structural engineer to safeguard your property against further damage.
If you are selling a home that has had subsidence, or buying one, our local teams can talk you through it. Book a valuation or contact your nearest Jones Robinson branch:
Devizes: 01380 730200
Didcot: 01235 816222
Lambourn & Hungerford: 01488 73337
Marlborough: 01672 556640
Newbury: 01635 35010
Pewsey: 01672 556640
Related Articles:
Level 2 vs Level 3 Survey: Which House Survey Do You Need?
What are the three main searches when buying a house
What are the ideal humidity levels in your house?