

TL;DR: If an estate owes inheritance tax but there is no cash to cover the bill, you have several options: draw from the deceased's bank account via the Direct Payment Scheme, pay the tax on property in annual instalments, take out an executor loan, or sell estate assets once probate is in place. This guide covers each option in order of simplicity, including what changed under the Finance Act 2026.
In this blog
- Why so many estates have no cash to pay inheritance tax
- How much inheritance tax will the estate owe?
- Step one: check the Direct Payment Scheme first
- Can you pay inheritance tax without selling the property?
- Can you pay inheritance tax on property in instalments?
- What is an executor loan and how does it work?
- Can HMRC let you pay after probate?
- Selling estate assets to pay the bill
- Life insurance, business relief and other options
- What to do first
- Frequently asked questions
Most executors expect paperwork. Few expect a tax bill they cannot actually pay.
Inheritance tax usually has to be paid, at least in part, before you can obtain a grant of probate, which is the legal authority to deal with the estate and sell its assets. When the bulk of an estate sits in a property rather than a bank account, that creates a genuine deadlock: you cannot sell the property without probate, but you cannot get probate without paying the tax first. It is a circular problem, and it affects more families as the tax take grows. HMRC's annual receipts bulletin shows inheritance tax raised £8.5 billion in the 2025 to 2026 tax year, up from £3.5 billion in 2006 to 2007, while the main tax-free threshold has not moved since 2009.
The good news is that the deadlock has solutions. This guide covers each one in order, starting with the simplest, and explains what the recent changes under the Finance Act 2026 mean for estates with business or agricultural assets, and for pensions.
Why So Many Estates Have No Cash to Pay Inheritance Tax
Inheritance tax must be paid to HMRC by the end of the sixth month after the month of death. In most cases at least some of it must be paid before a grant of probate can be issued. When an estate's value is held in property rather than savings or investments, executors face a situation where they cannot access or sell the assets they need to pay the bill.
This is not an unusual position. House prices across much of England have grown significantly over the past two decades, pushing many estates over the £325,000 nil-rate band (the tax-free threshold) without the deceased ever having large cash savings to match.
The nil-rate band, which is the amount an estate can pass on free of inheritance tax, has been frozen at £325,000 since April 2009 and the Finance Act 2026 extends that freeze to 5 April 2031. As property values have risen and the threshold has stood still, more families find themselves dealing with an IHT bill for the first time. Understanding your options before the six-month deadline arrives makes the process significantly more manageable.
How Much Inheritance Tax Will the Estate Owe?
Before you work out how to pay, it helps to know roughly what the bill will be. These are the main figures for deaths in the 2026 to 2027 tax year.
| Rule | What it means |
|---|---|
| Nil-rate band | £325,000 per person, frozen until 5 April 2031 |
| Residence nil-rate band | Up to £175,000 extra when a home is left to children (including adopted, foster or stepchildren) or grandchildren, taking the threshold to £500,000. Reduced by £1 for every £2 the estate is worth over £2 million. Also frozen until 5 April 2031 |
| Spouses and civil partners | Anything left to a spouse or civil partner is normally tax-free, and any unused threshold can pass to the survivor, so a couple leaving their home to children or grandchildren can pass on up to £1 million between them (subject to the £2 million taper) |
| Tax rate | 40% on the value above the threshold (36% on some assets if 10% or more of the net estate goes to charity) |
| Payment deadline | End of the sixth month after the death. HMRC charges interest on anything paid late |
| Instalments | Tax on land, buildings and some business assets can be paid in 10 equal yearly instalments |
| Pensions | Most unused pension funds and death benefits will count towards the estate for deaths on or after 6 April 2027 |
Source: GOV.UK, How Inheritance Tax works, HMRC thresholds and interest rates and Finance Act 2026. The £1 million couple figure combines two nil-rate bands and two residence nil-rate bands.
A simple example shows how the cash problem arises. Someone who is single dies leaving a house worth £670,000 to their children and £30,000 in savings. Ignoring debts, funeral costs and other reliefs, the estate is worth £700,000 and the threshold is £500,000, so inheritance tax is 40% of £200,000, which is £80,000. The savings cover less than half of that, and the rest of the value is locked up in bricks and mortar.
Step One: Check the Direct Payment Scheme First
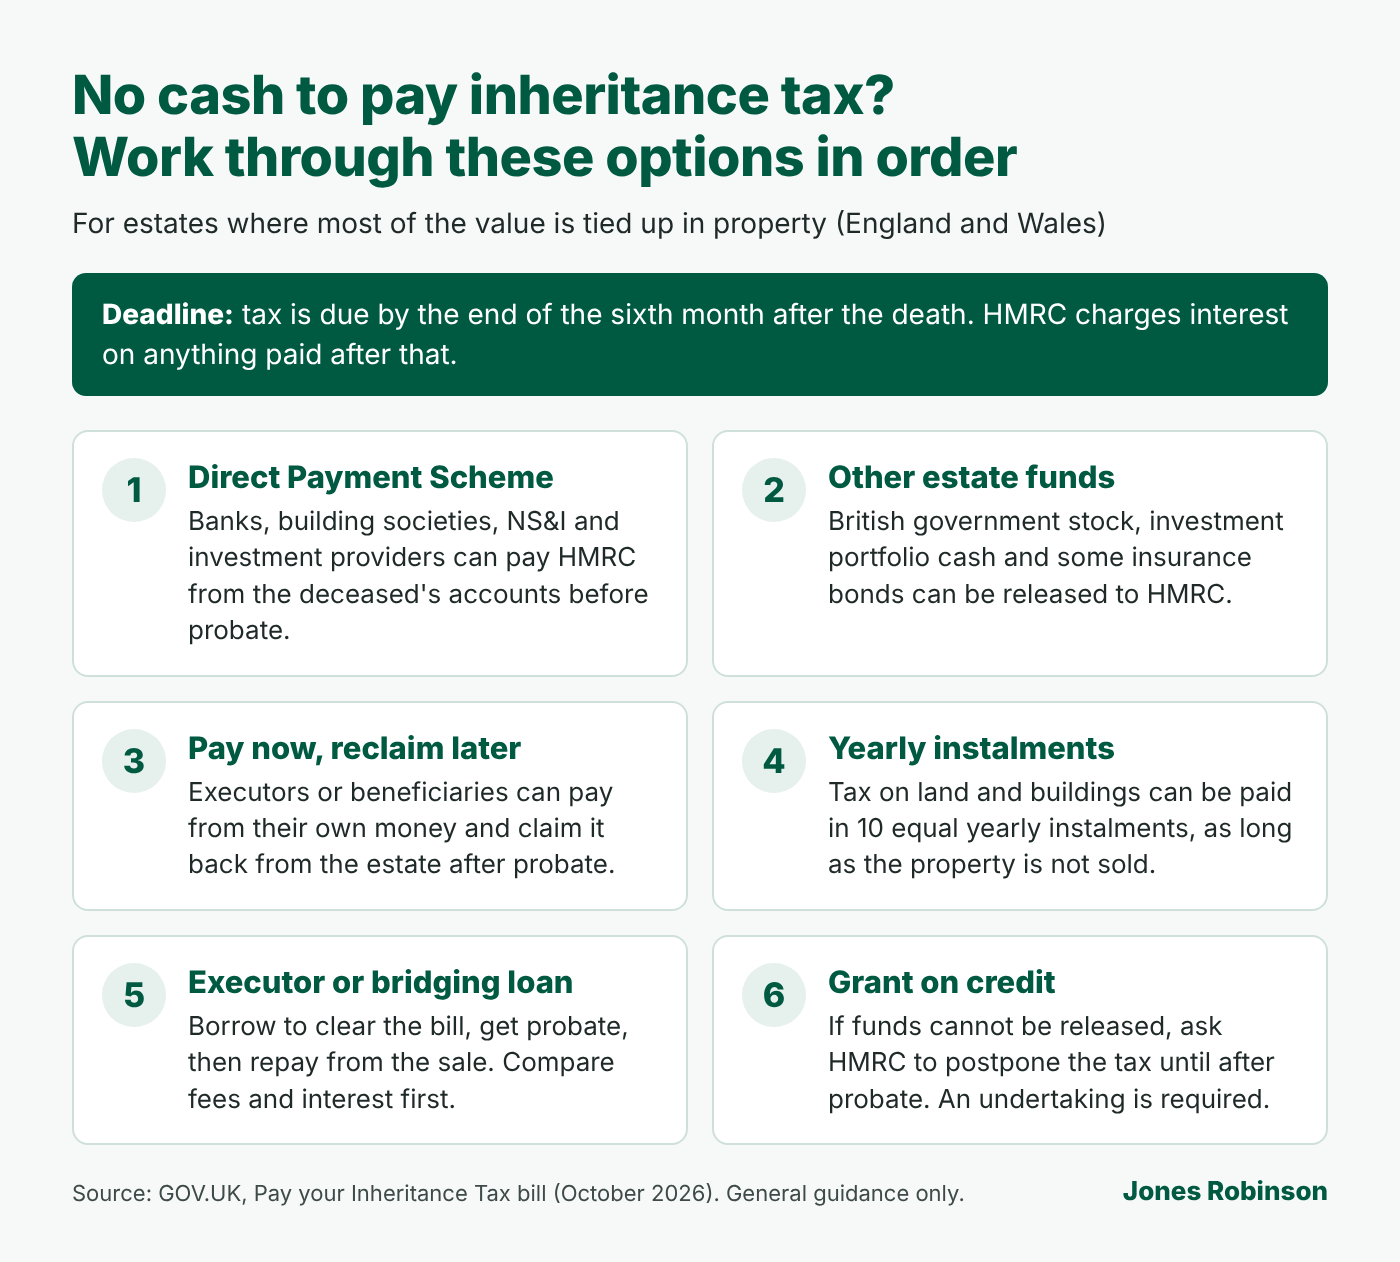
Before exploring loans or asset sales, the first thing any executor should check is whether the deceased held UK bank, building society, NS&I or investment accounts with funds available. Under the Direct Payment Scheme (DPS), these providers can pay some or all of the inheritance tax straight to HMRC from the deceased's accounts, and you can start the process before probate is granted. Many providers take part, but not all, so ask each one.
The Direct Payment Scheme works like this:
- Ask each bank, building society or investment provider to register you as the personal representative (each has its own process).
- Get an inheritance tax payment reference number from HMRC.
- Fill in form IHT423 and send it to the provider, using a separate form for each account you want to pay from.
- Send the inheritance tax account (form IHT400) and supporting pages to HMRC.
- The provider pays HMRC. In England and Wales, HMRC then sends you a code so you can apply for probate online.
This route bypasses the deadlock entirely if the accounts hold enough to cover the bill. If they cover only part of the liability, the DPS reduces the shortfall, and you use one of the other options below to cover the rest.
The GOV.UK guide to paying from the deceased's accounts sets out the current forms and address.
Can You Pay Inheritance Tax Without Selling the Property?
Often, yes. If the family wants to keep the house, or simply does not want a rushed sale, these are the main routes HMRC recognises:
- Other money in the estate. Besides bank accounts, HMRC says cash held in share and investment portfolios can sometimes be released directly to pay the tax, and some insurance and investment bond providers will do the same. Ask the stockbroker, fund manager or provider.
- Paying from your own funds. Executors (or beneficiaries) can pay from their own bank account or a joint account they held with the deceased, then claim the money back from the estate once probate is granted.
- Instalments. Tax on the house can be spread over 10 years, as long as it is not sold (see below). If the home is let while you pay, the rent can help fund the instalments, and our landlord services can help if you have not let a property before.
- Buying out the other beneficiaries. Where one beneficiary wants to keep the home, they may be able to raise a mortgage to buy the others out once the estate is ready to transfer it. Our guide to buying someone out of a house explains how that works, and our mortgage advice team can talk through borrowing.
Keeping the property means paying interest on later instalments, plus any borrowing costs, so compare the total cost with a sale and talk it through with your solicitor before deciding.
Can You Pay Inheritance Tax on Property in Instalments?
If the estate includes property or land, HMRC allows the inheritance tax due on those assets to be paid in ten equal annual instalments rather than as a single lump sum. You must say on form IHT400 that you want to pay this way. The first instalment is due by the end of the sixth month after death, and further instalments fall due on the same date each year. There is no interest on the first instalment unless it is paid late, but each later instalment carries interest on the full outstanding balance. If the property sells before all instalments are paid, the remaining tax becomes due in full.
This option is particularly useful when the estate's beneficiaries intend to keep the property rather than sell it. It allows them to obtain probate (using an executor loan or DPS to cover the first instalment and any tax on other assets), then pay down the remaining liability each year from rental income or other funds.
Assets that qualify for the instalment option include:
- Land and buildings, including houses, even if they are rented out
- Shares or securities that gave the deceased control of a company
- Certain unlisted shares, depending on their value and size of holding
- Assets that qualify for Business Relief or Agricultural Relief, and the net value of a business run for profit
Assets that do not qualify include cash, most listed shares and most savings-type investments. The GOV.UK guidance on paying in yearly instalments sets out the full eligibility criteria.
One point that often catches executors out: if the estate sells the property at any point before the ten years are up, all remaining IHT and any accrued interest becomes payable. If selling is the plan, the instalment route may not save you anything in the long run.
What Is an Executor Loan and How Does It Work?
An executor loan (sometimes called a probate loan or inheritance tax loan) is short-term borrowing taken specifically to pay an inheritance tax bill. It allows the executor to clear the IHT liability, obtain probate, and then repay the loan once the estate's property or other assets have been sold. Bridging loans serve a similar purpose and are often used when a property sale is close to completion but funds are not yet available.
Terms vary between lenders. Many look to the estate's assets for repayment, but check exactly what the loan is secured against and whether you are being asked for any personal guarantee, which matters if you are acting as executor for someone else's estate.
Before committing to either option, ask the lender:
- What is the interest rate, and is it fixed or variable?
- Are there arrangement fees, and how are they charged?
- What is the loan term, and are there early repayment charges?
- What happens if the property takes longer to sell than expected?
Interest and fees reduce the amount beneficiaries ultimately receive, so it's worth working through the numbers before committing. Compare the total cost with HMRC's own late payment interest, and bear in mind that a bridging loan may be the right call if exchange of contracts is already agreed and you need funds quickly.
Can HMRC Let You Pay After Probate? (Grant on Credit)
If you genuinely cannot release funds from the estate and cannot pay another way, you can ask HMRC to postpone some or all of the tax until after probate is granted. This is known as a grant on credit. It is a fallback rather than a first choice, and HMRC sets clear conditions:
- Send the completed IHT400 and a letter headed "Grants on credit" with your IHT reference, confirming you cannot release funds using the methods above and stating the most you can pay now.
- You are still expected to pay as much as you can before HMRC will support the application.
- You will be asked to sign an undertaking, a legally binding promise to pay within an agreed timescale.
- If the tax will come from a house sale, there must be an accepted offer and an estimated date for exchange of contracts. HMRC will not accept an open-ended promise.
- HMRC may register a notice of the inheritance tax charge against the property at HM Land Registry. It does not stop the sale, but buyers may ask for it to be removed before completion.
Interest still runs on any tax paid after the six-month deadline. The full process is on GOV.UK: apply to postpone payment of Inheritance Tax. Because an accepted offer is needed, it can help to get the property valued and marketed early. Our guide on whether you can sell a house before probate is granted explains what is possible at that stage.
Selling Estate Assets to Pay the Bill
For most property-heavy estates, selling the main residential property is ultimately how the inheritance tax gets settled. The typical sequence is: use the DPS, an executor loan, the instalment option or a grant on credit to obtain probate, then sell the property and use the proceeds to repay whatever was borrowed or outstanding.
Getting the property valuation right at the outset matters more than most executors realise. Your IHT bill is calculated based on the property's open market value at the date of death. An inaccurate valuation means either overpaying tax or, worse, underpaying and later facing extra tax, interest and possibly a penalty from HMRC.
If the estate includes a residential property in West Berkshire, Central Wiltshire, or South Oxfordshire, Jones Robinson can provide a professional valuation and manage the probate property sale process from instruction through to completion. For executors navigating both the legal and practical side of an estate sale, having an agent who understands how the sale process works and can coordinate with solicitors makes a material difference to how smoothly the process runs. Our guide to what a probate property is covers what buyers and sellers should expect.
Our conveyancing service can also support the legal side of the transaction, with a Contract Ready approach that prepares draft contracts before an offer is accepted, reducing delays once a buyer is found.
Care costs raise the same question earlier in the process, and we cover it in selling your parents’ house to pay for care.
Life Insurance, Business Relief, and Other Options Worth Checking
If the deceased held a whole-of-life insurance policy written in trust, the payout normally sits outside the taxable estate and can be used to pay the inheritance tax bill. A policy written in trust is one placed into a legal trust arrangement so that the payout on death goes to the trustees rather than into the estate, which means the money can usually be paid out without waiting for probate.
The key phrase is "written in trust." A policy that was not placed in trust forms part of the estate and may increase the IHT liability rather than offset it. It's worth checking with the insurer or a solicitor to confirm how the policy was set up.
Beyond life insurance, there are a few other options that apply in specific circumstances:
- Business Property Relief (BPR) and Agricultural Property Relief (APR). These reliefs can reduce or eliminate the IHT due on qualifying business or agricultural assets. From 6 April 2026, under the Finance Act 2026, 100% relief is limited to the first £2.5 million of combined qualifying agricultural and business property per person, where previously there was no cap. Qualifying assets above this level get 50% relief. The allowance can pass between spouses and civil partners, so a couple can pass on up to £5 million of qualifying assets with full relief. For assets inherited from 6 April 2026, tax paid in instalments on property qualifying for these reliefs is interest-free if each instalment is paid on time. Anyone administering an estate with farm or business assets should verify the relief position with a solicitor before assuming the liability is fixed.
- British government stock. Gilts held by the deceased can be used to pay IHT directly, by writing to Computershare Investor Services, which runs the scheme, and sending HMRC a letter and form IHT400. HMRC says the transfer can take up to four weeks, so it is not the route to choose if you need probate quickly.
- Family loans. Beneficiaries or family members can lend the executor funds to cover the bill, then be repaid from the estate once probate is obtained. A written agreement setting out the repayment terms avoids misunderstandings later.
None of these options work in every situation. The right approach depends on what the estate contains, how quickly probate is needed, and what the beneficiaries' longer-term intentions are for the assets.
Gifting property during your lifetime carries its own rules and risks, which we cover in what is a deed of gift for property in the UK.
What to Do First
If you're administering an estate with an IHT bill and limited cash, the order of steps matters.
Start with the basics: check whether the deceased held UK bank, building society or investment accounts with funds available, and ask each provider about the Direct Payment Scheme. If the estate includes property, check whether the instalment option applies and whether that buys enough time. If you need probate quickly and there is no cash in the estate, an executor loan is usually the most straightforward route to unlock the process, with a grant on credit as the fallback once a buyer has been found. If you are not sure of the final figure, you can make payments on account before the deadline, which reduces the interest HMRC charges.
Getting the property valuation right from the start reduces the risk of paying more tax than necessary. If the estate includes residential property in our area, from Newbury and Hungerford to Marlborough, Devizes and Didcot, contact the Jones Robinson team for a valuation and a straightforward conversation about what happens next. Alternatively, book a valuation online.
One final note: the rules around inheritance tax have changed significantly in the last 12 months. Before finalising any IHT calculation, particularly one involving business assets, farmland, or pension funds, take advice from a probate solicitor. The figures can shift materially depending on which reliefs apply.
Frequently Asked Questions
Can you get probate without paying inheritance tax first?
Usually you need to pay at least some of the inheritance tax before probate is granted. The exception is a grant on credit, where HMRC agrees to postpone some or all of the tax until after probate because you cannot release funds from the estate. In practice, the Direct Payment Scheme or an executor loan often resolves the deadlock first.
How long do you have to pay inheritance tax?
Inheritance tax must be paid by the end of the sixth month after the month in which the person died. If the person died in January, the IHT deadline is 31 July. HMRC charges interest on any outstanding amount after the deadline. Its published rate for late inheritance tax was 7.75% a year from 9 January 2026, and the rate moves with market rates, so check the current HMRC rate. You can make payments on account before the exact figure is confirmed, which stops interest accruing on the amount paid.
What if the estate's value is tied up and there is no cash at all?
Inheritance tax is only due where there is value in the estate, so the usual problem is that the value cannot be reached yet, not that it does not exist. Work through the options above in order and, if none of them work, apply to HMRC for a grant on credit. HMRC will expect clear evidence that you cannot release funds, and a probate solicitor can help you make the case.
Does selling an inherited property trigger additional tax?
Selling an inherited property may give rise to Capital Gains Tax if the property has increased in value between the date of death and the date of sale. The starting point for CGT purposes is the probate value (the property's market value at the date of death), not its original purchase price. If the executors sell, they can use the estate's annual CGT exempt amount for the tax year of death and the following two tax years. A solicitor or accountant can confirm whether CGT applies and at what rate.
Have the inheritance tax rules changed recently?
Yes, significantly. The Finance Act 2026 became law on 18 March 2026. From 6 April 2026, 100% Business Property Relief and Agricultural Property Relief is limited to £2.5 million per person, with qualifying assets above this level getting 50% relief. For deaths on or after 6 April 2027, most unused pension funds and pension death benefits will be included in the taxable estate, with personal representatives responsible for reporting and paying the tax; death in service benefits from a registered pension scheme are excluded. The nil-rate band (£325,000) and residence nil-rate band (£175,000) are frozen until 5 April 2031.
Do beneficiaries have to pay the inheritance tax themselves?
Not normally. The executor or administrator pays inheritance tax from the estate before the inheritance is passed on. HMRC may contact a beneficiary directly in some cases, for example where they received a gift in the seven years before the death, or where the personal representative could not or did not pay.
This article is for general informational purposes only and does not constitute legal or financial advice. Inheritance tax rules are complex and subject to change. Please seek advice from a qualified solicitor or financial adviser before making decisions about an estate.
Our Branches
Newbury Estate Agents
Devizes Estate Agents
Didcot Estate Agents
Lambourn & Hungerford Estate Agents
Marlborough Estate Agents
Pewsey Estate Agents