
TL;DR: A derelict property in the UK is usually priced well below a comparable finished home because of the cost and risk of the work, but most standard mortgage lenders will not lend on it. The realistic finance routes are cash, a bridging loan, or a specialist refurbishment mortgage. Budget for a RICS Level 3 survey, check listed building and conservation area status, check whether the empty homes council tax premium applies, and, if the home has been empty for at least two years before work starts, make sure your builder applies the 5 per cent reduced VAT rate to qualifying work.
Most guides on how to buy a derelict property in the UK skip the one fact that decides whether a project ever happens. Standard residential mortgage lenders will not lend on a property they class as uninhabitable, which is the single biggest reason these purchases collapse before exchange. If the roof is not watertight, the kitchen or bathroom is missing, or the property has structural defects, the high street is not an option.
That changes everything about how you find a property, finance it, and time the works. It is also the part of the process that buyers across our patch (West Berkshire, Central Wiltshire and South Oxfordshire) most often misjudge, whether they are looking at a rural cottage in the Lambourn Valley or a period town house in Devizes or Marlborough.
In this blog
- What counts as a derelict property in the UK?
- How to find a derelict property in the UK
- Can you get a mortgage on a derelict property?
- Surveys and structural checks
- Planning permission, listed buildings and conservation areas
- The real cost picture: purchase, renovation, tax and VAT relief
- Common pitfalls and contingency planning
- After the renovation: selling, letting or living in
- Frequently asked questions
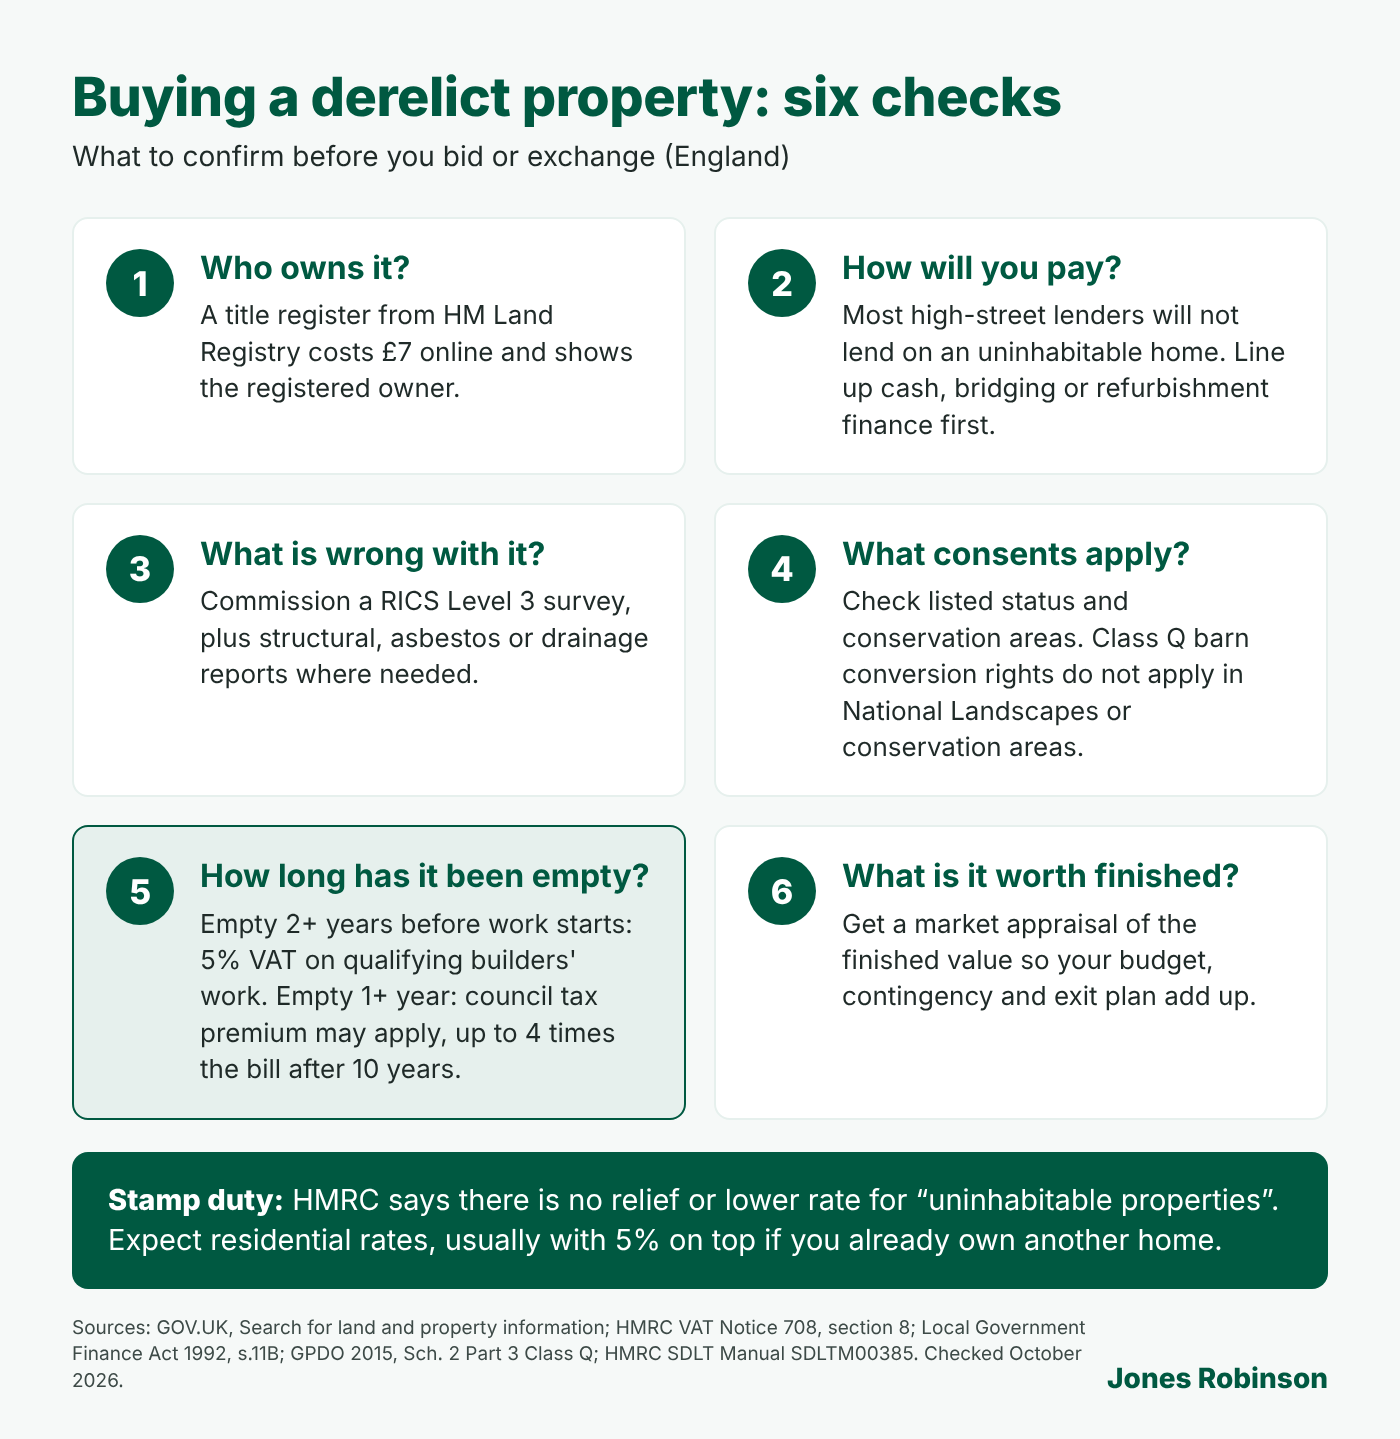
What Counts as a Derelict Property in the UK?
A derelict property in the UK is one that cannot be safely lived in at the point of sale. There is no single legal definition, but the council tax test on GOV.UK is a useful benchmark: a property is only considered derelict if it is not possible to live in it (for example because of weather damage, rot or vandalism) and it would need major structural works to make it wind and watertight again. For mortgage purposes, the working test is simpler: does the property have a watertight roof, a working kitchen and bathroom, and functional services? If not, it usually falls into the uninhabitable category lenders will not touch.
The terms get used loosely, so it helps to separate them:
- Derelict: a property in advanced disrepair, often missing essential services like water, electricity, or heating, or lacking weatherproofing.
- Uninhabitable (lending definition): a property that cannot be lived in immediately because it lacks a working kitchen, bathroom, watertight roof, or has structural defects.
- Abandoned: a property left vacant for a long period with no maintenance and no sign the owner intends to use it. A council can occasionally conclude that a long-ruined building's residential use has been abandoned, in which case planning permission is needed to use it as a home again. This is decided case by case, so ask the planning department early.
How to Find a Derelict Property in the UK
Derelict properties are found through five main routes: property auctions, mainstream portals with the right search keywords, council empty homes officers, HM Land Registry ownership searches, and spotting them on the ground. Most never appear on Rightmove with the word "derelict" in the listing, so one channel is rarely enough. Build a pipeline across at least three.
Auctions
Auctions are the most reliable way to find derelict stock. National and regional auction houses run regular catalogues covering southern England, and some local agents, including Jones Robinson through our virtual auction service, also sell this way. At a traditional auction a 10 per cent deposit is usually due on the day, and completion normally follows within about four weeks, but always check the conditions of sale for each lot. That window rules out most standard mortgage applications, which is why cash and bridging finance dominate auction purchases.
If you plan to bid, register early, get the legal pack at least a week ahead, and have finance pre-approved. Read the special conditions: lots often carry buyer-paid legal costs not shown in the guide price.
Online Portals and Specialist Websites
Rightmove and Zoopla both list run-down properties, but you need to search by descriptor rather than by the word "derelict". Useful terms include "in need of modernisation", "renovation project", "scope to improve", "in need of refurbishment" and "investment opportunity". Locally, keep an eye on our rural properties for sale, where cottages and farm buildings needing work do come up.
Council Empty Homes Officers
Many councils have an empty homes officer or team responsible for bringing long-term empty properties back into use. They will sometimes put interested buyers in touch with owners open to a private sale, and they can confirm how long a property has been empty, which matters for the 5 per cent VAT rate later. If a building is dangerous or neglected rather than simply empty, GOV.UK directs the public to report a derelict or abandoned building to the council's building control team, which can prompt action and sometimes a sale.
HM Land Registry Searches
If you spot a property that looks abandoned but is not on the market, a title register from HM Land Registry will usually tell you who owns it. Through the GOV.UK land and property search it costs £7 to download a title register or title plan, or £11 per document for an official copy by post. This is how the more serious renovators source off-market deals: once you have the owner's name and address, you can write to them directly.
Not all land is registered, particularly where a property has not changed hands for decades. If the search finds nothing, ask neighbours, the parish council and the council's empty homes team. Where ownership is uncertain, read our guide to possessory title before going further.
The "Driving Around" Method
Walking or driving target streets and rural lanes turns up properties that are derelict but unlisted online: boarded-up windows, overgrown gardens, piled-up post and a sagging roof line. Check the Land Registry before approaching the owner, and never enter without permission.
Can You Get a Mortgage on a Derelict Property?
Standard residential mortgage lenders will not lend on a property classed as uninhabitable. If a derelict property lacks a working kitchen, working bathroom, watertight roof, or has structural issues, most high-street lenders will decline outright. The four realistic finance routes are cash, a bridging loan, a refurbishment mortgage, or mortgage retention, where a lender holds back funds until specified works are completed.
A lender cannot value an uninhabitable home reliably or easily recover its money by selling it, which is why short-term bridging lenders take on properties the high street rejects.
| Finance Route | Typical Use | Speed | Cost | Exit |
|---|---|---|---|---|
| Cash | Auction lots; quick purchases | Fastest | No borrowing costs | Sale or refinance once habitable |
| Bridging loan | Auction and quick-completion buys | Fast, often days or weeks | Interest charged monthly, plus arrangement, valuation and legal fees | Refinance to mortgage or sale of property |
| Refurbishment mortgage | Light or heavy refurb projects | Slower than bridging | Higher rates than standard residential | Convert to standard mortgage after works |
| Mortgage retention | Properties needing defined essential works | Standard mortgage timeline | Standard rates with funds held back | Retained portion released once the agreed works are signed off |
Speeds and costs vary by lender and case; take advice before relying on any route.
Bridging loans are usually repaid within about 12 months, and rates and fees vary widely, so compare the total cost rather than the headline monthly rate. Every bridging lender will want a credible exit strategy: how you will repay, usually by sale or refinance. A refurbishment mortgage releases money in stages as work completes. Mortgage retention only suits properties close to mortgageable on day one, so it rarely works for true derelict stock. If you are buying without borrowing, our guide to what counts as a cash buyer explains what sellers and auctioneers will expect to see.
Speak to a broker before you bid or offer. Jones Robinson works with Firstxtra Financial Services for mortgage advice, which covers refurbishment products and specialist lending alongside standard residential cases.
Surveys and Structural Checks
A derelict property needs a RICS Level 3 Survey, ideally carried out by a Chartered Surveyor (MRICS), not a Level 2 HomeBuyer Report or a basic mortgage valuation. A Level 3 Survey is the most detailed homebuyer survey available. It costs more than a Level 2 because the inspection and report take longer, so get quotes from more than one surveyor and tell them up front that the property is derelict.
What a Level 3 Survey Covers
Level 3, the full Building Survey, is the only RICS level that gives a usable picture of a derelict property's defects. The surveyor inspects every accessible area and reports on:
- Structural movement, including settlement, subsidence and bowing walls
- Damp readings across walls, floors and roof spaces
- Timber condition, including dry rot, wet rot, and infestation
- Roof and chimney condition
- Electrical and plumbing services (visual inspection only; specialist tests separate)
- Materials that may contain asbestos, flagged for specialist testing
- Drainage where visible
The report sets out repairs in order of urgency and flags where specialist follow-up is needed. If the surveyor finds cracking, our guide to subsidence cracks explains which patterns tend to be cosmetic and which need a structural engineer.
Specialist Additional Reports
For most derelict purchases, the Level 3 Survey is the starting point, not the full picture. Depending on findings you may also need:
- A structural engineer's report if movement, cracking or roof spread is suspected
- An asbestos refurbishment survey for any pre-2000 building before works begin
- A drainage CCTV survey if the mains drainage condition is unknown
- An electrical installation condition report (EICR) before any rewiring
They cost far less than finding the same problems after exchange.
Planning Permission, Listed Buildings, and Conservation Areas
Renovation work on a derelict property may require planning permission, Listed Building Consent, or both. Listed Building Consent is separate and stricter, covering any alteration, inside or out, that affects a listed building's character. Conservation areas add controls on external work, demolition and trees.
Planning Permission Basics
Internal repairs and like-for-like refurbishment usually do not need planning permission. Extensions, loft conversions with dormers, change of use (for example, agricultural to residential) and demolition often do. Permitted development rights let some works go ahead without a full application, but they are restricted in conservation areas, and on a listed building you will still need Listed Building Consent for relevant works even where planning permission is not required.
Listed Building Consent
Listed Building Consent is applied for through the council's planning system and usually assessed with input from a Conservation Officer. The threshold is low: removing a fireplace, replacing windows with modern equivalents or changing internal layouts can all need consent. Doing such work without it is a criminal offence under section 9 of the Planning (Listed Buildings and Conservation Areas) Act 1990, and the council can require the owner to put the building back at their own cost.
Before you exchange, check the entry on Historic England's National Heritage List for England and have a pre-application conversation with the Conservation Officer. Our guide to buying a Grade II listed property covers the wider responsibilities of ownership.
Conservation Areas
A conservation area is designated by the local authority for its special architectural or historic interest. West Berkshire alone has 53 conservation areas, including Newbury Town Centre, Hungerford, Lambourn and Thatcham, so the chance that a derelict property in our patch is affected is real. In Wiltshire and South Oxfordshire, check each council's maps for towns such as Marlborough, Devizes and Pewsey.
The most common practical effects are tighter control of window replacement (often requiring matching materials and proportions), the need for planning permission to demolish buildings above a certain size, and tree work: under the government's guidance, you must give the council six weeks' notice (a section 211 notice) before most work on a tree.
Barn Conversions and Class Q
Rural derelict stock often includes redundant agricultural buildings. Class Q is a permitted development right that allows certain agricultural buildings to become homes without a full planning application, subject to prior approval from the council. Under the General Permitted Development Order, Class Q does not apply where:
- the site is in a conservation area, a National Landscape (formerly an Area of Outstanding Natural Beauty), a National Park or a World Heritage Site
- the site is a Site of Special Scientific Interest or contains a scheduled monument, or the building is listed
- the site was not part of an established agricultural unit on 24 July 2023 (or for at least 10 years before development begins, if it joined later)
- the new home could not meet the nationally described space standard, or there is no suitable existing access to a highway
That first point matters locally. Lambourn and the Lambourn Valley sit within the North Wessex Downs National Landscape, so for farm buildings there Class Q is not available and a full planning application is the realistic route. Elsewhere in rural Wiltshire and Oxfordshire, Class Q may be worth investigating, but check the designations on the council's planning map first.
None of this is legal advice. Confirm a property's status with the council and Historic England before exchanging, and instruct a solicitor with renovation experience. Jones Robinson's conveyancing service handles sales-linked legal work across our catchment.
The Real Cost Picture: Purchase, Renovation, Tax, and VAT Relief
The total cost of buying and renovating a derelict property has six main components: the purchase price, Stamp Duty Land Tax, survey and legal fees, finance costs, renovation works, and holding costs, which can include the empty homes council tax premium. Two things partly offset the bill: a purchase price that reflects the work needed, and the 5 per cent reduced VAT rate on qualifying renovation work.
| Cost Component | What to Expect |
|---|---|
| Purchase price | Below comparable finished homes, reflecting the cost and risk of the works |
| Stamp Duty Land Tax | Standard residential rates for most buyers; usually 5% on top if you already own another residential property |
| Survey and legal fees | Level 3 survey, specialist reports and conveyancing; get quotes before you commit |
| Finance costs (bridging) | Monthly interest plus arrangement, valuation and legal fees |
| Renovation works | Fixed-price contractor quotes plus a contingency; 5% VAT on qualifying work if empty for 2+ years |
| Holding costs | Council tax (a premium of up to 300% may apply to long-term empty homes), insurance, utilities, security |
Source: GOV.UK Stamp Duty Land Tax residential rates; HMRC VAT Notice 708; Local Government Finance Act 1992, section 11B.
The Purchase Price Discount
The discount on a derelict property reflects the cost and risk of the works, not undervaluation, and competition at auction can narrow it quickly. Work backwards from the finished value, minus works, finance, fees and contingency.
Stamp Duty Land Tax
Stamp Duty Land Tax (SDLT) is paid to HM Revenue and Customs when buying property or land in England and Northern Ireland over a set threshold. Standard residential rates apply to most derelict purchases, and if you already own another residential property you will usually pay 5 per cent on top. You can estimate the charge with our stamp duty calculator.
You may hear that an uninhabitable property qualifies for the lower non-residential rates. Be very careful. HMRC's own guidance states that there is no tax relief or lower SDLT rate for "uninhabitable properties", that only a very limited number of properties genuinely stop being dwellings, and that a very high proportion of repayment claims in this area are wrong. Get specialist advice before taking any other position, and be wary of repayment agents who promise otherwise. Our guide to the hidden costs of buying a home covers the other purchase costs to budget for.
The Empty Homes Council Tax Premium
The Empty Homes Premium is extra council tax that councils in England can choose to charge on homes that have been unoccupied and substantially unfurnished for a continuous period. Since 1 April 2024, councils have been able to charge it once a home has been empty for one year (previously two). Under section 11B of the Local Government Finance Act 1992, the maximum premium is 100 per cent for homes empty for under five years, 200 per cent from five years, and 300 per cent from ten years. As GOV.UK puts it, that can mean up to four times the normal bill. The MHCLG Council Taxbase 2025 release recorded 153,000 dwellings in England being charged the premium in 2025, up 27.9 per cent on 2024.
The premium follows the property, not the owner. The empty period is measured against the home itself and breaks of up to six weeks are ignored, so you can inherit a premium the previous owner was paying. A few points work in your favour:
- You may not have to pay the premium for up to 12 months while an empty home is undergoing major repairs or structural alterations (standard council tax still applies unless another discount or exemption does).
- If you are making major improvements and cannot live in the property, you can ask for it to be removed from the council tax list until the work is finished.
- A genuinely derelict home that cannot be lived in does not receive a council tax bill for as long as it stays empty.
Speak to the council before exchange to confirm the current status and what might apply during your works, and tell them as soon as the property can be lived in.
VAT Relief at 5%
The reduced rate of VAT on renovating empty homes is one of the few genuine financial wins of a derelict purchase. Under HMRC VAT Notice 708, Section 8, a VAT-registered builder can charge 5 per cent instead of 20 per cent on renovating or altering a home that has not been lived in during the two years immediately before the work starts. The key conditions:
- What qualifies: the builder's work on the fabric of the home, the building materials they supply and fit, and works in the immediate site for water, power, heat, access, drainage, security and waste disposal.
- What does not: professional fees (architects, surveyors and consultants), scaffolding, hire of goods, landscaping, and fitting goods that are not building materials, such as carpets or fitted bedroom furniture. These stay at 20 per cent, as do materials you buy yourself.
- Occasional use counts: if the home was used as a second home at any point in the two years, the reduced rate does not apply. Squatters, property guardians and non-residential use such as storage can be ignored.
- Consents matter: if the work needs planning permission or building regulations approval that has not been granted, the builder must charge the standard rate.
The rate is charged by your contractor, not reclaimed by you, and the contractor needs evidence that the property has been empty for two years or more. HMRC accepts electoral roll, council tax and utility records, and a letter from the council's Empty Property Officer is enough on its own. On £100,000 of qualifying work, the difference between 20 and 5 per cent VAT is £15,000.
Grants and Other Help
Do not plan a derelict purchase around grant funding. The main national scheme likely to be relevant is the Boiler Upgrade Scheme, which offers property owners in England and Wales £7,500 towards an air source or ground source heat pump when replacing fossil fuel heating, plus an extra £1,500 until March 2027 where the home is heated by oil or LPG with no mains gas, which is common in rural properties. Our article on heat pumps explains how they work in practice. Some councils also offer loans or grants for empty homes, so ask the empty homes team what is currently available.
Common Pitfalls and Contingency Planning
The four most common reasons derelict property projects fail are underestimating renovation costs, finance falling through after exchange, hidden defects discovered during works, and planning or listed building consent refusals. The safeguards are simple: a 15 to 20 per cent contingency on top of priced works, finance approval before bidding, and planning status confirmed before exchange rather than after.
Cost Underestimation
Online calculators are starting points, not budgets. Costs vary widely with size, condition and specification, so build your number from a fixed-price quote by a contractor who has walked the site, ring-fence the contingency and do not spend it on upgrades.
Finance Falling Through
Approval in principle is not a formal offer; the lender can still pull out if the valuer flags an issue. Keep your lender briefed on the legal pack and survey findings.
Hidden Defects
A survey cannot see behind plaster, under floors or inside roof voids. Allow for damp behind sound-looking walls, asbestos in pre-2000 buildings and lath-and-plaster ceilings that fail once disturbed.
Consent Refusals
A pre-application discussion with the planning team and Conservation Officer costs little and tells you whether your plans are likely to be supported. Exchanging on a listed building without that is one of the easiest ways to lose money.
After the Renovation: Selling, Letting, or Living In
A well-finished renovation should be valued in line with comparable homes, but any profit depends on what you paid and spent. Whatever your plan, involve an agent before the works finish.
Selling On
Plan the listing while the works are in their final phase. Professional photography, marketing copy that explains the renovation, and a new Energy Performance Certificate (EPC), so the rating reflects your improvements, all help buyers understand what they are paying for. A Market Appraisal before completion tells you the likely finished value before you commit further capital. Book a Valuation and we can give you a Market Appraisal across our six branches.
Letting Out
If you plan to let, compliance starts before the first tenant moves in: a Gas Safety Certificate, an Electrical Installation Condition Report (EICR) renewed at least every five years, a valid EPC, a smoke alarm on every storey used as living accommodation, and a carbon monoxide alarm in any room with a fixed combustion appliance (excluding gas cookers), as set out in the government guidance for landlords. Tenancies now run under the Renters' Rights Act, so read our summary of what the Act means for landlords in Berkshire and Wiltshire. Our lettings team (ARLA Propertymark members) and property management service can handle the paperwork, inspections and compliance.
Living In
If you are moving in yourself, the practical points are insurance (renovation policies often do not cover occupied buildings, so update cover before you move), council tax (the empty homes premium falls away once it is your sole or main residence; tell the council when the works finish), and reconnecting utilities. The 5 per cent VAT rate depends on the home being empty for two years before the work started, not on who lives there afterwards, and HMRC confirms the work stays at the reduced rate if the occupier moves in after the work has begun.
Conclusion
A derelict purchase works when the finance, survey, consents and contingency are settled before you commit. Get those right and the lower price and VAT relief work in your favour; get them wrong and you risk exchanging on something you cannot afford to finish.
If you are looking at a derelict or run-down property in West Berkshire, Central Wiltshire or South Oxfordshire, we can help with a Market Appraisal of the likely finished value, mortgage advice through Firstxtra, and sales or letting support once the work is done. Book a Valuation, browse our properties for sale, or contact your nearest branch in Newbury, Didcot, Marlborough, Devizes, Pewsey or Lambourn.
Frequently Asked Questions
Can you get a mortgage on a derelict property in the UK?
Most standard residential lenders will not lend on a property classed as uninhabitable. If it lacks a working kitchen, bathroom or watertight roof, or has structural issues, the realistic options are cash, a bridging loan or a refurbishment mortgage. Speak to a broker before bidding, since auction completion deadlines of around four weeks rule out most standard mortgage applications.
How much cheaper is a derelict property?
There is no reliable standard percentage. Derelict homes usually sell for less than comparable finished homes because of the cost and risk of renovation, and competition can narrow the gap. Work out the finished value, subtract the full cost of works, finance, fees and a contingency, and treat that as the most you can sensibly pay.
What is the empty homes council tax premium?
Councils in England can charge extra council tax on homes that have been unoccupied and substantially unfurnished for at least one year: up to 100 per cent extra for under five years, 200 per cent from five years and 300 per cent from ten. The empty period runs with the property, so a buyer can inherit it, although you may be excused the premium for up to 12 months during major repairs or structural alterations.
Do I need planning permission to renovate a derelict house?
It depends on the work. Internal repairs and like-for-like refurbishment usually do not. Extensions, change of use, demolition in a conservation area and any work affecting the character of a listed building typically need permission or consent.
Can I get VAT relief on renovating an empty home?
Yes, if the home has not been lived in during the two years immediately before the work starts. A VAT-registered builder can then charge 5 per cent instead of 20 per cent on qualifying work and the building materials they supply. Professional fees, scaffolding and materials you buy yourself stay at 20 per cent. A letter from the council's Empty Property Officer is sufficient evidence.
What survey should I get for a derelict property?
A RICS Level 3 Survey, ideally by a Chartered Surveyor (MRICS). Depending on its findings, you may also need a structural engineer's report, an asbestos refurbishment survey or a drainage CCTV survey.
Can I claim a derelict house in the UK?
Only in very limited circumstances. Adverse possession can let someone apply for ownership after occupying a property continuously as if they owned it, without permission, for 10 years if it is registered or 12 years if not, and the registered owner can object. Squatting in a residential building is a criminal offence that can lead to six months in prison, a £5,000 fine or both, according to GOV.UK. The better route is to find the registered owner via HM Land Registry and approach them directly.